Posted by Altair Media on September 26, 2026 · Leave a Comment
Five ways to turn minority budget talks into a durable strategy
Rob Jetten has invited opposition parties to help reshape the Netherlands’ 2027 budget. The invitation matters, but agreement will require more than adjustments to individual spending lines. Parties need a common view of the practical constraints, a genuine role in choosing priorities, and confidence that any settlement can survive both chambers and deliver results beyond 2027.
The Council of State offers a useful starting point. It says the Miljoenennota identifies the country’s long-term challenges clearly, but that the proposed budgets and tax measures do not yet fully reflect that analysis. The task is larger than finding enough votes for one year. It is to connect political agreement to a course the country can sustain.
Read More
Category: Strategic Briefings, Capital, Featured Headlines, Governance, Infrastructure, Insights, Society & Leadership, Strategy Governance · Tags: Budget Negotiations, European strategy, Miljoenennota 2027, Minority Government, Netherlands, Political Governance, Public Investment, Serie - Governing Without a Majority, Strategic Briefings
Posted by Altair Media on September 25, 2026 · Leave a Comment
The Netherlands’ €516.8 billion question: can a minority government fund tomorrow while negotiating its way through today?
The Dutch government plans to spend €516.8 billion in 2027. Almost half of that goes to healthcare and social security. At the same time, the country needs to strengthen defence, expand its power grid and make room for housing and industry. The ‘Miljoenennota’ sets out these ambitions. Its test is whether the choices behind them will hold.
For Prime Minister Rob Jetten’s minority government, that test is financial and political. It must keep long-term plans credible while finding parliamentary majorities for the budget. Five questions reveal where the pressure lies.
🟦 Where does the money actually go?
Healthcare and social security together account for €258 billion in planned spending. Those commitments support the country today, but they also leave limited room to change course quickly. New priorities must compete for money, people and the capacity to put plans into practice. Announcing an investment is easier than making it happen.
🟦 Which choices have already been postponed?
The government has dropped its proposed direct link between the state pension age and life expectancy, withdrawn a planned cut to the maximum daily wage, and delayed other social security measures. These decisions create room for talks with employers, unions and Parliament. They also leave questions about how the costs of an ageing society will be managed later.
🟦 Can a minority government protect a long-term plan?
Every budget requires negotiation. Without a fixed parliamentary majority, the government has to assemble support for measures that may impose costs now and deliver results years later. That is particularly difficult for energy infrastructure, housing and industrial capacity: each depends on decisions that remain credible beyond one budget debate.
🟦 How much room do the European rules leave?
The projected deficit of 2.9% of GDP in 2027 remains below the EU’s 3% limit, and debt remains below 60%. Yet those figures do not settle the question. The Council of State expects Dutch spending to grow by 4.7% in 2027, above the 3.5% rate allowed under the agreed European spending path. The immediate limits are respected; the longer-term trajectory is under strain.
🟦 Who carries the cost if decisions keep moving forward?
The Council of State says the Miljoenennota describes the country’s structural challenges clearly, but that the proposed budgets and tax measures do not yet match that analysis. It warns that, without further choices, a disproportionate share of the burden could fall on working people, younger citizens and future generations.
The signal
The central risk in this budget is a widening gap between the future the Netherlands says it must build and the decisions it is prepared to sustain. A minority government can close that gap. The measure of success will be whether its parliamentary agreements preserve the long-term investments and reforms on which its plans depend.
Image credit
Illustration: Altair Media / AI-generated
Caption
Prime Minister Rob Jetten faces a €516.8 billion budget. The stacked blocks represent competing spending priorities and are illustrative, not a proportional chart.
Category: Signal, Capital, Energy Infrastructure, European Governance, Featured, Financial Governance, Financial Infrastructure, Governance, Insights, Strategy Governance · Tags: economic governance, European Fiscal Rules, Future Generations, Miljoenennota 2027, Minority Government, Netherlands, Public Finance, Rob Jetten, Serie - Governing Without a Majority
Posted by Altair Media on September 24, 2026 · Leave a Comment
Europe has the demand. What it lacks is a semiconductor market that behaves as one
SIGNAL | Five days ago, Altair Media argued that European semiconductor policy has a blind spot. Europe spends heavily on fabs, research and production capacity, but pays far less attention to the industrial demand that ultimately determines whether those investments become commercially viable.
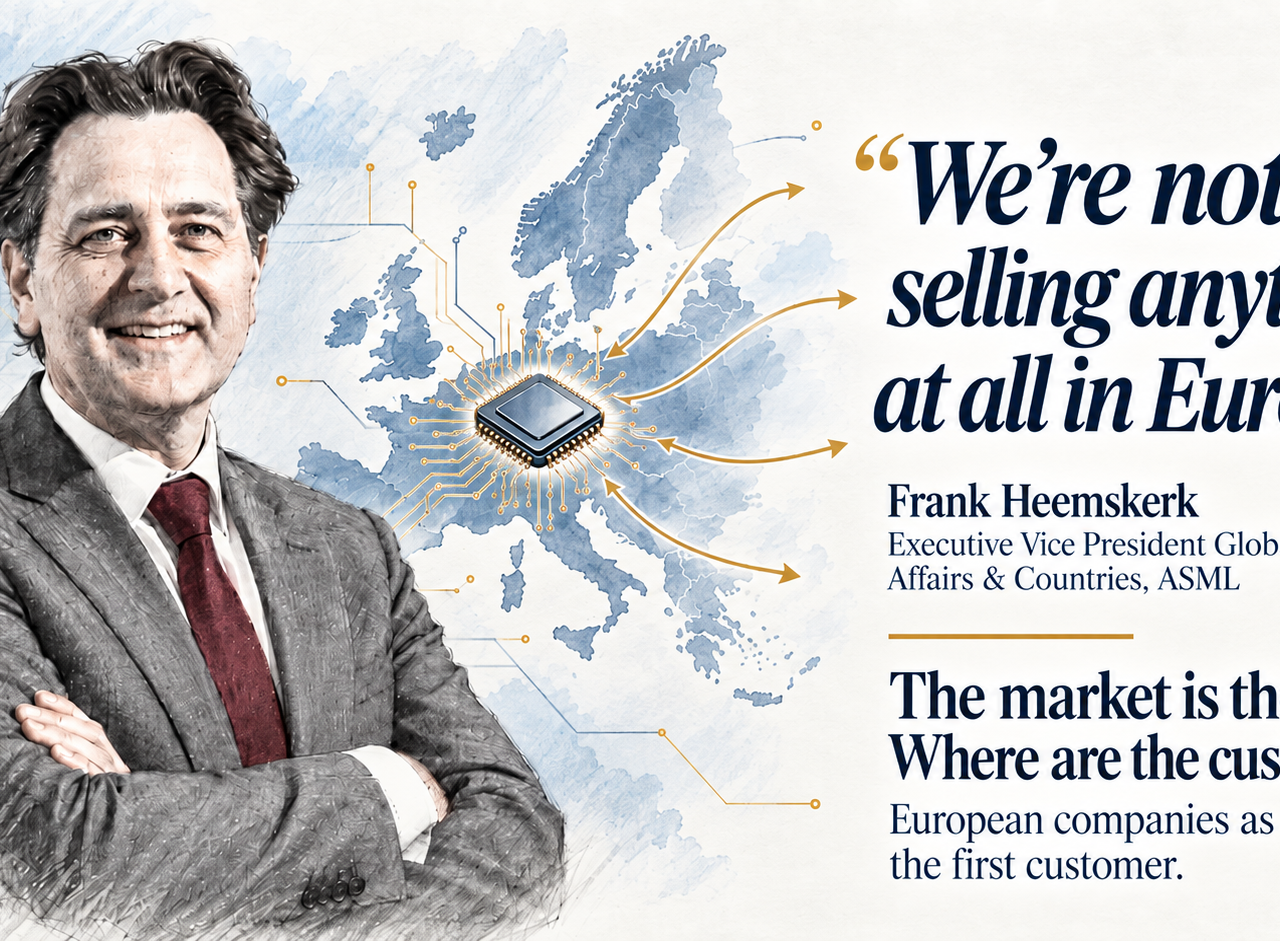
This week, ASML turned that abstract problem into a remarkably concrete one. Speaking in Amsterdam, Frank Heemskerk, Executive Vice President Global Public Affairs & Countries at ASML, described the situation in unusually blunt terms:
“We’re not selling anything at all in Europe.”
That is the paradox. Europe is home to ASML — and to some of the world’s largest automotive, industrial, telecom and aerospace companies. The demand for chips is clearly there.
So why does so little of it translate into semiconductor investment at home?
Read More
Category: Signal, Capital, Digital Governance, Digital Infrastructure, European Governance, Featured Headlines, Financial Governance, Financial Infrastructure, Governance, Infrastructure, Photonics, Strategy Governance · Tags: ASML, chip manufacturing, European Industry, European Innovation Council, Industrial Strategy, Photonics, Semiconductors, Strategic Autonomy
Posted by Altair Media on September 23, 2026 · Leave a Comment
The EIB, EIF, KfW, Bpifrance and CDP already support strategic investment—but rarely as one system
Europe wants to build new factories, energy networks and battery plants. But even a promising project can struggle to find money. A new technology may work in a laboratory without having proved itself at industrial scale. Customers may be interested, but unwilling to sign contracts for the next twenty years.
Banks often wait until construction is complete. Pension funds usually want stable and predictable income. The project may be important for Europe and still be too risky for private finance.
Europe already has the institutions
Several public financial institutions were created to help solve this problem. The European Investment Bank (EIB, European Union) provides long-term loans and guarantees for major projects. The European Investment Fund (EIF, European Union) works through banks and investment funds to improve access to finance, particularly for smaller companies.
The Kreditanstalt für Wiederaufbau (KfW, Germany) supports investment through public programmes and commercial banks. Bpifrance (France) provides guarantees, loans and equity to companies. Cassa Depositi e Prestiti (CDP, Italy) finances infrastructure and strategic development.
A project can be important for Europe and still be too risky for private finance.
Together, these institutions already have capital, expertise and public backing. They can support projects that commercial investors consider too early, too complex or too uncertain. But they rarely operate as one European system.
Read More
Category: Strategic Briefings, Capital, European Governance, Featured Headlines, Financial Governance, Financial Infrastructure, Governance, Infrastructure, Insights · Tags: Bpifrance, Cassa Depositi e Prestiti, European Investment Bank, European Investment Fund, Industrial Investment, KfW, Public Banking, Risk Sharing, Serie - Can Europe’s Banks Build an Industrial Investment Platform?
Posted by Altair Media on September 19, 2026 · Leave a Comment
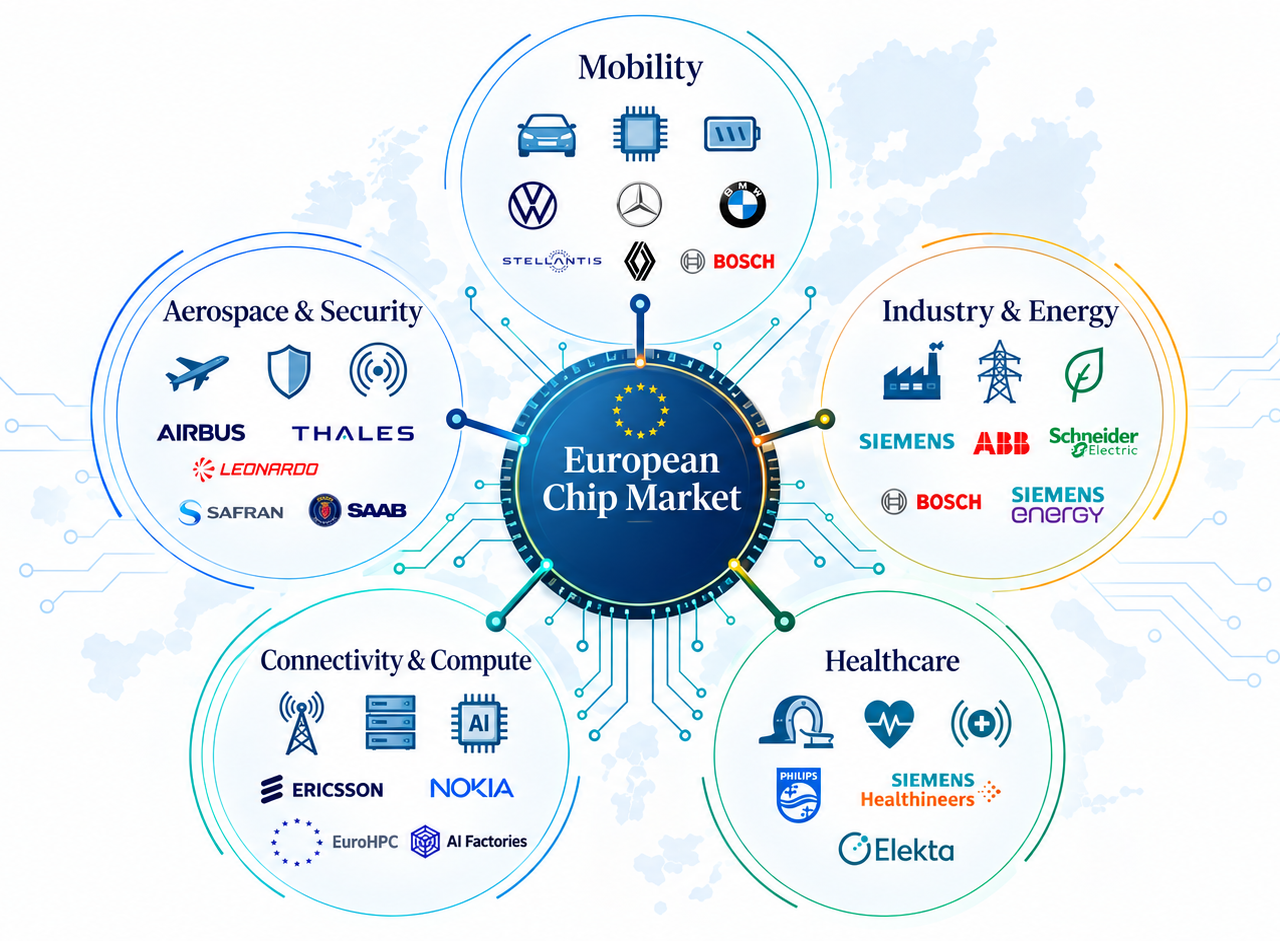
Europe has spent years asking where its next semiconductor fab should be built. Chips Act 2.0 points towards a different question: which European industries will create the demand that makes those fabs worth building?
SIGNAL | ASML may be Europe’s most indispensable technology company. Its machines sit at the centre of advanced semiconductor manufacturing, supported by one of the most sophisticated industrial ecosystems the continent has ever built. Yet almost none of that demand is European.
In 2025, ASML generated €32.7 billion in sales. Around €28 billion came from Asia. EMEA accounted for just €524 million, with another €4.7 million in the Netherlands itself. On ASML’s system-sales measure, only 1% of machines shipped to EMEA.
Europe builds the machines on which much of the global semiconductor industry depends. But the factories using them are overwhelmingly somewhere else. That imbalance is usually described as a production problem. It may be something more fundamental.
Europe has a semiconductor market problem.
Read More
Category: Signal, Capital, Digital Infrastructure, European Governance, Featured Headlines, Infrastructure, Insights, Photonics, Strategy Governance · Tags: AI infrastructure, ASML, Brainport, European Chips Act, European Industry, Industrial Strategy, Semiconductors, Technology Sovereignty
