Posted by Altair Media on November 13, 2026 · Leave a Comment
Mohamed Alabbar and the private capital that builds markets around places
Mohamed Alabbar is usually described as a property developer, but that description misses something important. Through Emaar, he has spent three decades combining homes, shopping, hotels, entertainment and public space into places designed to generate their own demand. The real product is not simply the building. It is the economic activity that begins to form around it.
Alabbar is the founder and Managing Director of Emaar Properties, while his wider business interests extend across e-commerce, hospitality, food, finance and international development. Emaar itself has delivered more than 130,000 residential units and built some of Dubai’s most recognisable assets, including Burj Khalifa and Dubai Mall.
But Downtown Dubai reveals the more interesting model. A conventional developer builds homes because people already want to live in a particular location. Alabbar helped develop a destination in which residences, offices, hotels, retail, restaurants, entertainment and landmarks reinforced one another.
People did not simply buy apartments. They bought access to a place in which retail benefited from tourism, hotels benefited from attractions, property values benefited from public space and global visibility, and restaurants and entertainment increased footfall across the district.
That creates a different form of capital allocation. Instead of waiting for a mature market and then supplying it, the developer commits capital to several interdependent assets in the expectation that the ecosystem itself will create demand.
The city as a platform
Alabbar has described his business in similar terms, arguing that property itself is relatively ordinary and that the real challenge is creating the life around it — food, landscaping, wellness, culture and services. That is a useful way to understand Emaar.
An apartment generates a sale, but the mall, hotel, entertainment venue and commercial district can continue generating activity long afterwards. In 2025, Emaar’s malls, hospitality, leisure, entertainment and commercial-leasing businesses generated AED 10.5 billion in recurring revenue and accounted for around 32% of group EBITDA.
The economics of a city are therefore very different from the economics of a building. A building can be completed and sold. A successful district has to continue attracting residents, visitors, businesses and capital, which means the developer becomes partly responsible for maintaining the network of experiences and services that keeps the location economically relevant.
In that sense, Emaar increasingly resembles a platform company whose platform happens to be physical.
Private capital inside a larger public vision
Alabbar’s model should not be mistaken for private enterprise operating independently of the state.
Dubai’s growth has depended on public infrastructure, aviation, regulation, long-term urban planning and an economic strategy designed to attract international capital, companies and residents. Alabbar himself has repeatedly credited the UAE’s wider institutional environment for allowing companies such as Emaar to plan and invest with confidence.
The interesting relationship is therefore not state versus private capital. It is what happens when public strategy creates the conditions in which entrepreneurial capital can move quickly.
Roads, airports, utilities and regulation make the city possible. Private developers then have to decide what people will actually choose to use, buy and visit. That introduces a different form of discipline from sovereign investment: a government can decide that a sector is strategically important, but an entrepreneur eventually has to discover whether customers agree.
Exporting the model
Alabbar has increasingly taken that approach beyond Dubai.
Through Eagle Hills, he is involved in large mixed-use developments across markets from Eastern Europe to the Middle East and Asia. These projects typically combine residential property with hospitality, retail, waterfronts and public destinations rather than treating individual buildings in isolation.
That suggests the model itself may be exportable: identify a location whose potential has not yet been fully priced, commit capital at scale and build enough complementary uses to change how the market perceives the place.
But exporting the formula also reveals its risk. Dubai combines tourism, aviation, infrastructure, international labour and capital flows in ways that cannot simply be reproduced elsewhere. A landmark building cannot manufacture an economy by itself, and an ambitious masterplan does not automatically create a community.
The developer can build the physical ecosystem, but it cannot command people to participate in it.
When confidence becomes concentration
That is the central tension in Alabbar’s model.
Building before demand is fully visible can create extraordinary value, but it can also commit enormous amounts of capital to assumptions about future population growth, tourism, property prices and consumer behaviour.
Emaar’s scale gives it significant advantages, yet it also means that execution matters enormously. In 2025 the company recorded property sales of more than $21 billion and entered 2026 with a substantial development backlog.
The larger the project, the more important it becomes to distinguish between creating demand and simply assuming that demand will eventually arrive.
Entrepreneurial capital therefore performs a different experiment from sovereign capital. It does not only ask what should be built. It asks whether people will come when it is built.
The entrepreneurial city
That makes Mohamed Alabbar a useful final figure in The New Architecture of Gulf Capital.
Yasir Al-Rumayyan uses sovereign wealth to create new domestic markets. Khaldoon Al Mubarak connects Abu Dhabi to global capabilities. Sultan Al Jaber moves capital between energy systems. Mohammed Al-Sowaidi converts concentrated resource wealth into a global portfolio for future generations.
Alabbar represents the next step: his capital has to turn strategy into places that people actually choose.
The success of that model cannot ultimately be measured by towers, square metres or property sales alone. It depends on whether the surrounding ecosystem becomes economically valuable enough to sustain itself after the original development decision has been made.
That is why Alabbar’s most interesting achievement may not be a building at all, but the idea that private capital can create a market by building the place in which that market wants to exist.
This article is part of The New Architecture of Gulf Capital, an Altair Media series examining how sovereign wealth, energy and private enterprise are shaping the region’s post-oil economy.
Credit
Illustration: Altair Media / OpenAI
Caption
Mohamed Alabbar, founder of Emaar Properties. His model of development combines real estate, retail, hospitality and public space into destinations designed to generate their own economic activity — turning the city itself into a platform for private capital.
Category: Financial Infrastructure, Capital, Featured, Infrastructure, Insights, Physical Infrastructure · Tags: Dubai, Emaar, entrepreneurship, Gulf Capital, Mohamed Alabbar, Private Capital, real estate, Serie - The New Architecture of Gulf Capital, Urban Development
Posted by Altair Media on November 12, 2026 · Leave a Comment
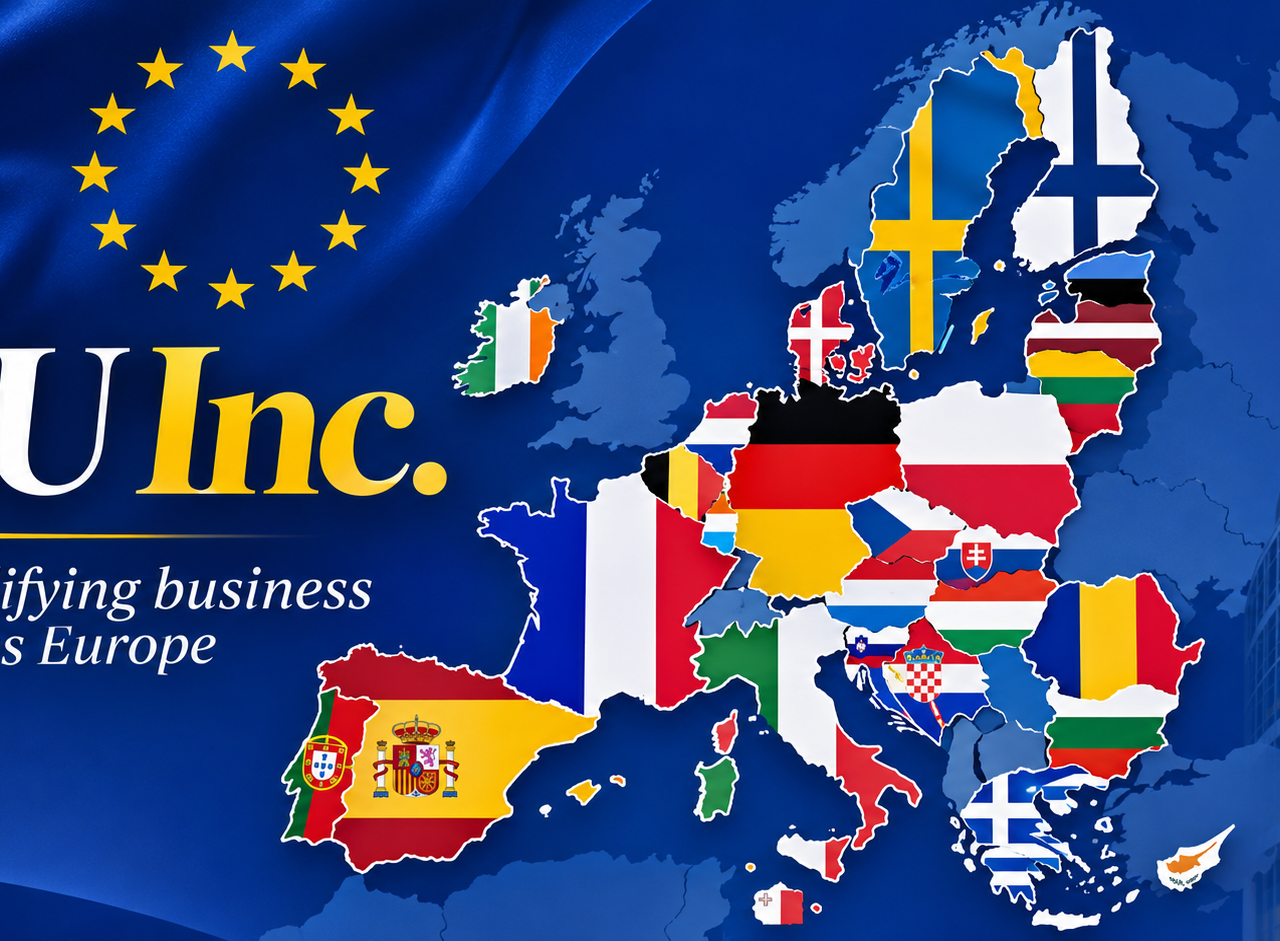
Removing the legal barriers to building and growing businesses across Europe.
One market, 27 legal systems
Europe has a single market of around 450 million consumers, yet starting and expanding a business across its borders remains surprisingly complicated. Entrepreneurs must navigate 27 national corporate legal systems and more than 60 different company forms, often involving different procedures, administrative requirements and costs.
This fragmentation has become part of the broader debate about European competitiveness. Reports by Enrico Letta and Mario Draghi have highlighted structural barriers that make it harder for European businesses to expand internationally, attract investment and compete with larger companies elsewhere.
The European Commission now wants to address part of this problem through EU Inc., a proposed common corporate framework introduced on 18 March 2026. On 23 October, the Council of the European Union adopted its negotiating position, moving the initiative further through the legislative process.
The objective is to make establishing, financing and growing a company across Europe considerably easier.
Read More
Category: European Governance, Altair News, Capital, Featured Headlines, Financial Governance, Financial Infrastructure, Infrastructure, Insights, Leadership & Institutions, Strategy Governance · Tags: Business Regulation, entrepreneurship, EU Inc., European Commission, European Competitiveness, European Single Market, european union, Startups and Scaleups
Posted by Altair Media on November 9, 2026 · Leave a Comment
Following the proceeds of fraud across accounts, institutions and borders.
In 2022, a German couple reported that they could no longer withdraw money from an online trading platform where they had invested their savings. Evidence from earlier searches led investigators to a company operating from Cyprus and Israel that allegedly supplied fraudulent websites to criminal groups. Investigators also identified suspected clients running call centres in the Western Balkans. In a coordinated operation on 3 November 2026, authorities arrested seven suspects and seized more than 100 servers. Investigators estimate losses of more than €4 million across the scheme. The amount returned to the couple remains undisclosed.
The first article in this series examined what Europe’s payment statistics can see. This one follows the money beyond the first transfer. The caller, the holder of the receiving account and the people who eventually collect the proceeds can all be in different countries. Finding one gives investigators a place to start. Recovering the money depends on finding where it is still within reach.
🟥 Who builds the scam?
In the German case, a deceptive advertisement could bring someone to a trading platform. A supposed broker would then build confidence and press for a larger deposit. The platform displayed apparent profits, giving the customer a reason to invest more. When the customer tried to withdraw the money, the operators stalled.
Investigators suspect the same supplier provided fraudulent websites to several groups. This is a form of scam-as-a-service. One company supplies the technology, while separate operators contact victims and persuade them to pay. Taking down a supplier can disrupt several operations at once. Recovering the proceeds requires following the payments those operations generated.
Other scams leave different records. A romance scam may start on a dating platform and move to private messages. A bank impersonation scam may start with a phone call that appears to come from a familiar number. A platform may hold records of a profile or an advertiser. A telecom provider may hold information about a call. The bank sees the payment instruction. Bringing those records together can help link complaints that initially appear unrelated.
🟥 What does the location of a scam centre tell us?
The European Commission and the UN Office on Drugs and Crime identify Southeast Asia as a major hub for organised scam centres. The model has spread to parts of Africa, the Middle East and eastern and southeastern Europe, among other regions. Some people making the calls are themselves victims of trafficking, recruited through false job offers and forced to defraud others.
A raid can establish where calls were made and who supplied the equipment. Following the payments can show who benefited. An operator abroad can direct a victim to a domestic account, making the transfer look familiar. Someone who had no contact with the victim may then move the money onwards.
🟥 Who controls the first receiving account?
A money mule receives funds on someone else’s behalf and passes them on, sometimes by withdrawing cash. Recruiters can use apparently legitimate job offers on social media. The account may be registered to a real person in the victim’s own country, even when the people directing the transfers operate abroad.
An account can also be opened using someone else’s identity. In a separate investigation announced in June 2026, Eurojust described a crypto laundering service that used accounts opened with stolen or purchased identities. Investigators identified more than 6,000 customer verification records linked to mule accounts. For banks and exchanges, the case illustrates why checks at account opening need to be backed by monitoring how the account is used.
The sending bank may see one customer paying a new recipient. The receiving bank may see several unrelated people paying into the same account, followed by rapid transfers out. An alert from the sending bank can give that pattern new meaning. If the proceeds have already moved, the receiving bank’s records can help identify the next account.
🟥 What changes when the money moves into crypto?
A scam can use crypto as a sales pitch, a way to move the money, or both. In an investigation involving Latvia, Lithuania and Ukraine, Eurojust reported that a call centre promoted fake crypto investments and used remote access software to gain access to victims’ funds. The operators moved money into bank accounts and cryptocurrency wallets.
Public blockchains can help investigators follow transfers between addresses. Identifying the people behind those addresses may require records from an exchange or another intermediary. Moving funds across blockchains or through a service that mixes transfers can make the trail harder to follow. When the holder tries to exchange crypto for conventional currency, the provider handling that conversion can offer a point of intervention. That service is known as an off-ramp.
The Bybit theft began with a breach at a crypto exchange. In February 2025, the FBI attributed the theft of around $1.5 billion in cryptoassets to North Korea and reported that some of the proceeds had been converted and dispersed across thousands of addresses. Whether funds came from an exchange breach or a misled saver, investigators face a similar question once the proceeds are in crypto. Can they identify a provider that still holds the assets, or one that can intervene when the holder tries to cash out?
🟥 When can the money still be stopped?
In July 2024, a Singapore commodities firm transferred $42.3 million to an account in Timor-Leste after receiving an email impersonating a supplier. The company discovered the deception four days later, when the genuine supplier said it had received no payment. Singapore police requested help through I-GRIP, INTERPOL’s Global Rapid Intervention of Payments mechanism. Authorities in Timor-Leste withheld $39 million in the receiving account and recovered more than $2 million through follow-up investigations. When INTERPOL announced the result, steps were under way to return the funds.
Most of the money was still in an account where local authorities could act. Once it moves again, the alert has to reach the next institution or jurisdiction. A freeze keeps assets in place while the case is investigated. The return of those assets is a separate outcome.
🟥 Can AMLA help shorten the time to intervention?
AMLA can support joint analysis by national financial intelligence units when suspicious activity spans several EU countries. Those units can compare reports and identify connections, such as the same recipients appearing in cases reported by banks in different countries. The EU’s anti-money-laundering directive also provides for national financial intelligence units to suspend transactions urgently in suspected money laundering cases, including at the request of a counterpart in another member state. Joint analysis and an urgent suspension are distinct functions.
A bank deciding whether to release a payment may have seconds. By the time analysts connect several reports, the original funds may already have moved. The practical question is whether those findings can reach the institutions that need them, through lawful channels, in time to flag the next payment into the same network.
Signal
A transfer can look ordinary to the bank that sends it and suspicious to the bank that receives it. The chance of getting the money back can depend on whether those two views meet before the next transfer.
This is the second article in AMLA and Europe’s Fraud Defences, a five-part series from Altair Media Europe on how Europe tracks criminal money and protects bank customers.
Credit
AI-generated illustration by Altair Media / OpenAI.
Caption
A red trail runs from a call centre through a financial district and branches across the river, illustrating how fraud proceeds can move between institutions and across borders.
Category: Signal, Capital, Featured, Financial Governance, Financial Infrastructure, Governance, Infrastructure, Insights · Tags: AMLA, Asset Recovery, Cross-Border Payments, Cryptoassets, Financial Intelligence, Money Laundering, Money Mules, Payment Fraud, Serie - AMLA and Europe’s Fraud Defences