Europe’s Public Banking Layer — Who Carries the First Risk?
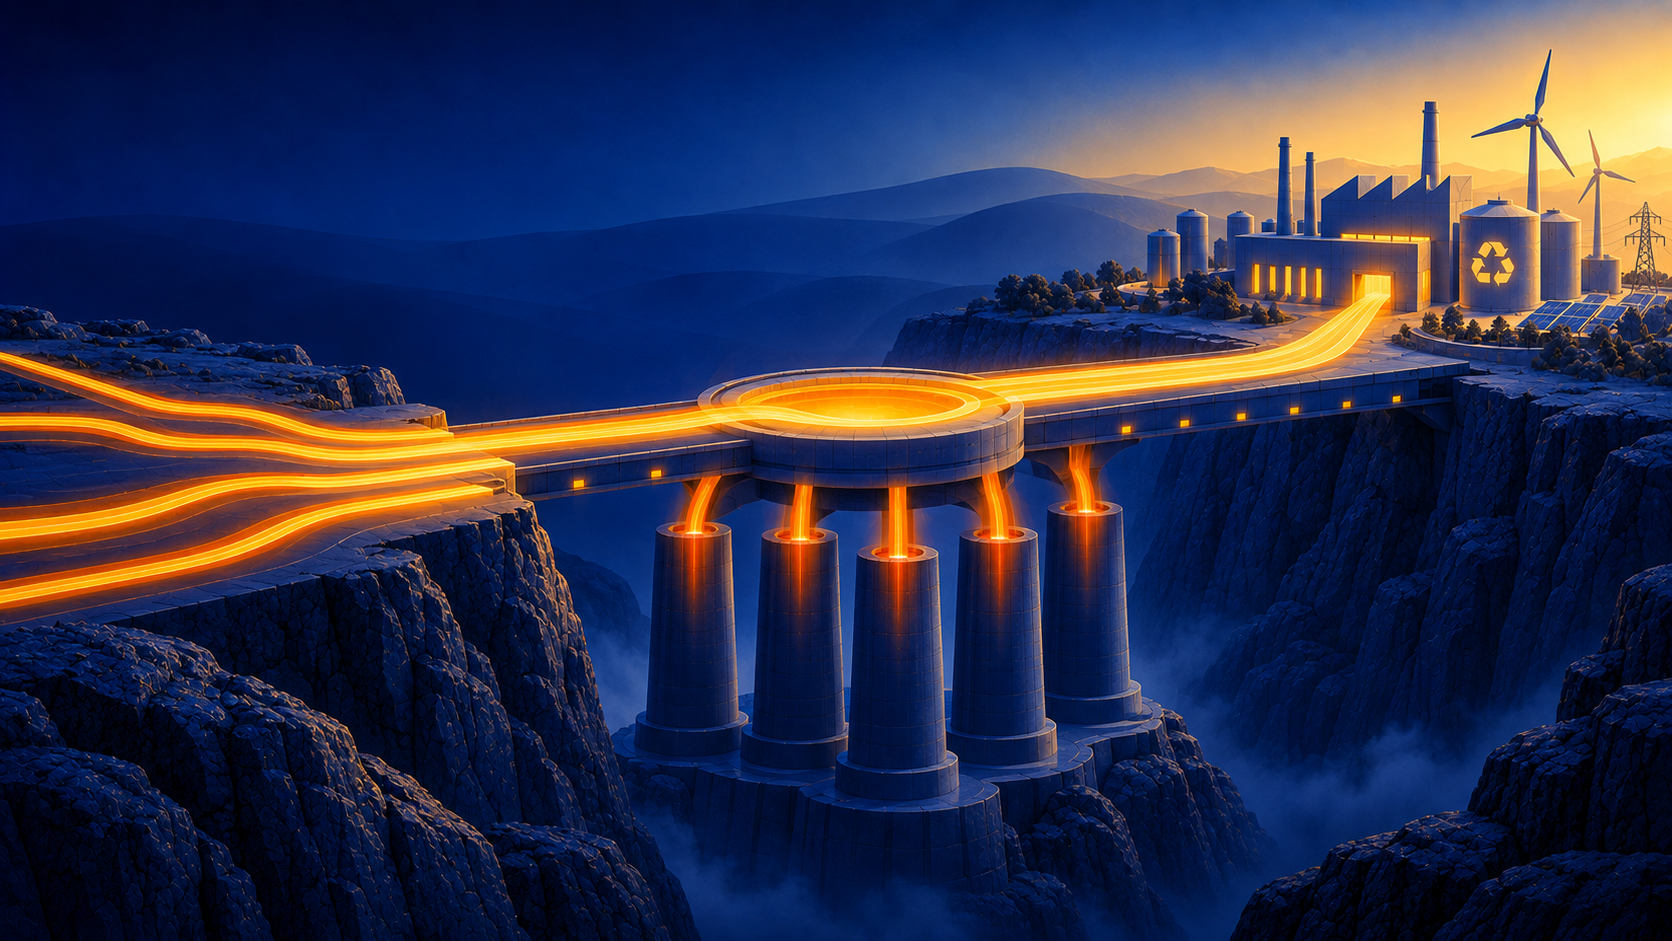
The EIB, EIF, KfW, Bpifrance and CDP already support strategic investment—but rarely as one system
Europe wants to build new factories, energy networks and battery plants. But even a promising project can struggle to find money. A new technology may work in a laboratory without having proved itself at industrial scale. Customers may be interested, but unwilling to sign contracts for the next twenty years.
Banks often wait until construction is complete. Pension funds usually want stable and predictable income. The project may be important for Europe and still be too risky for private finance.
Europe already has the institutions
Several public financial institutions were created to help solve this problem. The European Investment Bank (EIB, European Union) provides long-term loans and guarantees for major projects. The European Investment Fund (EIF, European Union) works through banks and investment funds to improve access to finance, particularly for smaller companies.
The Kreditanstalt für Wiederaufbau (KfW, Germany) supports investment through public programmes and commercial banks. Bpifrance (France) provides guarantees, loans and equity to companies. Cassa Depositi e Prestiti (CDP, Italy) finances infrastructure and strategic development.
A project can be important for Europe and still be too risky for private finance.
Together, these institutions already have capital, expertise and public backing. They can support projects that commercial investors consider too early, too complex or too uncertain. But they rarely operate as one European system.
Who carries the risk?
A company asking for public support must first invest its own money. That matters. If the entrepreneur cannot lose anything, weak projects can easily be passed to the taxpayer. Companies and their shareholders must remain responsible for the decisions they make.
Public institutions can then cover a clearly defined part of the risk. They may guarantee part of a bank loan. They may provide a loan that absorbs losses before more protected lenders are affected. They may support the first commercial use of a new technology or help during construction. This protection gives commercial banks more confidence to lend.
The public euro should not replace private capital. It should make private participation possible earlier.
Once the factory is operating and earning predictable income, pension funds, insurers or bond investors can enter. The public institution may then reduce its involvement and use its capacity for another project.
Why does this not happen at European scale?
The institutions already work with private banks and investors. European programmes such as InvestEU also show that shared guarantees are possible. But every institution has its own rules, priorities and methods.
A project approved by KfW in Germany does not automatically become acceptable to an insurer in France or a pension fund in Italy. The technical and financial checks may have to be repeated. Documents may use different definitions. Guarantees may cover different risks. National politics creates another barrier.
KfW answers to German public priorities. Bpifrance supports French development. CDP has an Italian mandate. Governments find it easier to defend public support when the factory, jobs and political benefits remain at home.
National finance and European industry no longer operate at the same scale.
Yet modern industry does not fit neatly inside national borders. A battery plant may use French technology, German machinery, Italian components and raw materials processed elsewhere in Europe. National finance and European industry no longer operate at the same scale.
A common European route
The institutions do not need to merge. They need to make their work understandable and usable across borders. A project could receive one common European assessment covering its technology, finances, customers and strategic value. Participating public banks could recognise that assessment instead of starting again.
They could then decide together which risk each institution is willing to carry. Commercial banks could join the same financing package. Pension funds and insurers could see clearly how the project had been assessed and which protections were in place.
The company would still carry its own business risk. Public guarantees would remain limited and transparent. Projects would only receive support when public involvement genuinely made an investment possible. This would create a European route from promising idea to operating industrial asset.
The missing connection
Europe’s commercial banks have balance sheets and customer relationships. Regional banks know where companies want to expand. Specialist banks understand sectors such as energy, shipping and infrastructure. Pension funds and insurers hold large pools of long-term capital.
Public money should not replace private capital. It should help private investors enter sooner.
The public banking layer should connect these parts. Its role is not to finance every factory or protect every investor from loss. Its role is to carry specific risks that prevent good projects from moving forward. The EIB, EIF, KfW, Bpifrance and CDP already do this separately.
The next step is to use common assessments, shared guarantees and clear rules to make their work cumulative.
Europe does not lack money. It does not lack banks. It does not lack public financial institutions. It lacks an agreement on how they should work together.
This Strategic Briefing is part of the series Can Europe’s Banks Build an Industrial Investment Platform?, examining how Europe’s banks, public institutions and capital markets could combine their different strengths to finance industrial transformation at continental scale.
Credit
Altair Media / OpenAI
Caption
Five public financial institutions form the foundations beneath Europe’s investment bridge. Their guarantees can help private capital cross the gap between a promising industrial project and a proven, operating business.
