Posted by Altair Media on October 5, 2026 · Leave a Comment
Europe wants stronger networks. Operators need a better way to earn from the capacity and certainty they deliver.
Europe wants faster networks, stronger digital infrastructure and less dependence on foreign technology. Operators are expected to build the foundations. But carrying more traffic does not automatically mean earning more money. The question is whether the business model can finance what comes next—and how operators can capture more value from the infrastructure they provide.
Six questions expose the gap between Europe’s network ambitions and the business case behind them.
Read More
Category: Telecom, Capital, Digital Governance, Digital Infrastructure, European Governance, Featured Headlines, Governance, Infrastructure, Insights, Signal, Strategy Governance · Tags: big tech, Business Models, Digital Infrastructure, digital networks act, European Competitiveness, net neutrality, Network Investment, telecom
Posted by Altair Media on October 2, 2026 · Leave a Comment
ESMA’s Data Day 2026 looks technical. The underlying question is broader: can Europe integrate its capital markets while the information beneath them remains fragmented?
Europe wants savings to move more easily into investment, companies to access deeper pools of capital and markets to function across borders. But capital cannot integrate faster than the information systems through which it is priced, reported and supervised. ESMA’s Data Day suggests that the Savings and Investments Union is increasingly becoming a data-infrastructure project as well.
On 24 November, ESMA will bring more than 200 regulators, market participants and other stakeholders together in Paris for its second Data Day. The programme covers reporting simplification, financial transaction reporting, integrated fund reporting, ESAP and crypto-asset monitoring.
The subjects sound technical. The implications are not.
Read More
Category: European Governance, Capital, Featured Headlines, Financial Governance, Governance, Infrastructure, Insights · Tags: ESAP, ESMA, European capital markets, European Finance, Financial Data, Financial Regulation, Market Infrastructure, Savings and Investments Union, Serie - How Europe Gets Capital Moving
Posted by Altair Media on October 1, 2026 · Leave a Comment
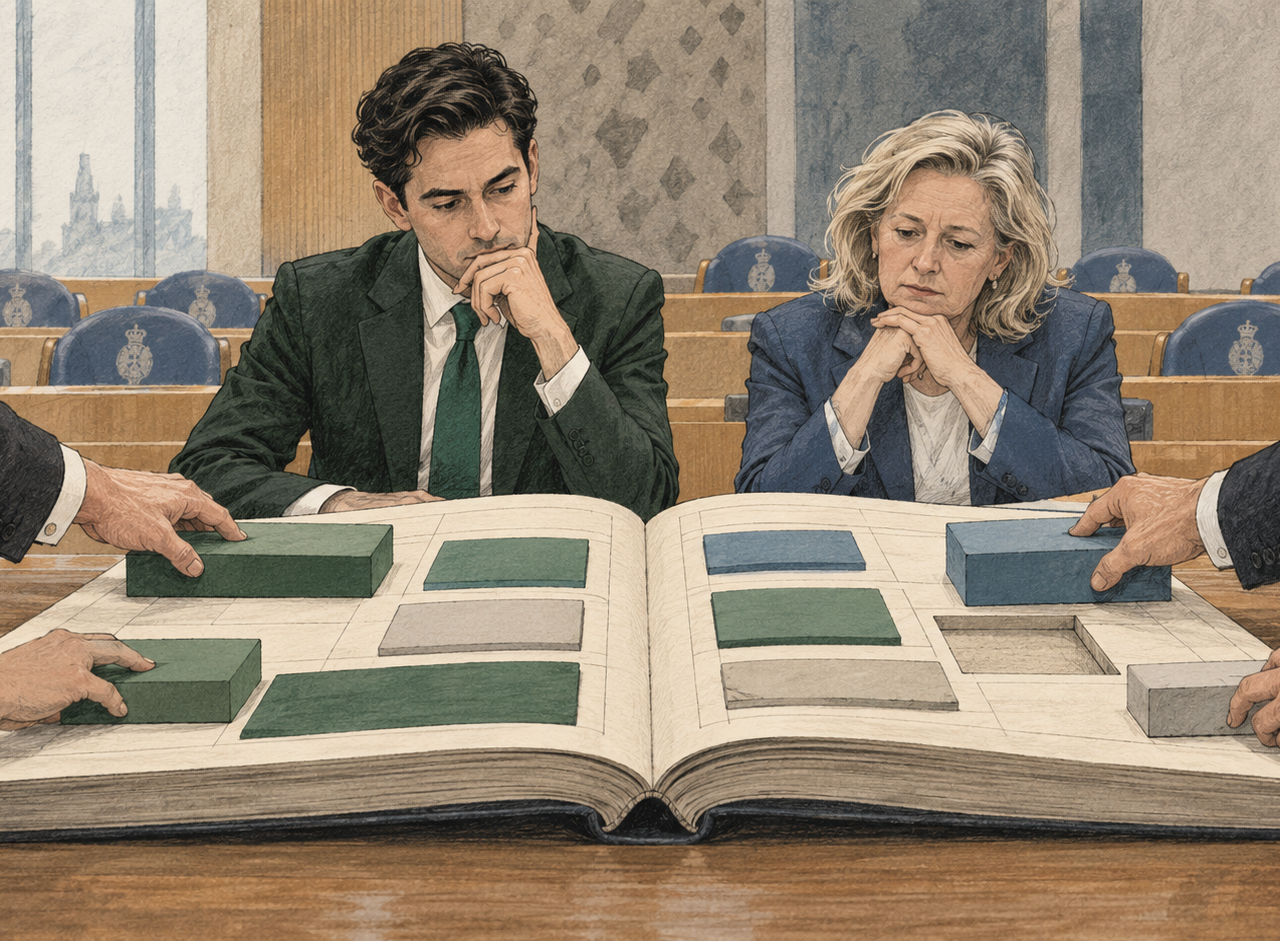
Every concession can bring the Dutch minority cabinet closer to a majority. Each one also raises a harder question: who pays?
The Dutch budget talks have begun to produce results. Proposed cuts to social security have been taken off the Social Affairs budget, opening a path to support from PRO and Volt. Yet the agreement has exposed another fault line. A tax plan meant to help finance a new system for taxing investment gains would draw more small savers into box 3. Parliament has pushed back and Finance Minister Eelco Heinen is looking for another solution.
The budget is moving. Five questions show why movement alone is not yet a settlement.
🟦 When a concession removes a saving, where does the bill go?
The social security dispute shows the difference between removing a measure and resolving its cost. Heinen has moved the expected savings, rising to €2.5 billion by the end of the cabinet’s term, to a central Finance Ministry reserve. He expects employers and unions to develop reforms and says the government will revisit the figures in the spring. If those savings do not materialise, other spending plans may face pressure. PRO has gained room for a social agreement; the cabinet has gained time. The financial outcome remains open.
🟦 Can a tax reform survive its own funding plan?
Heinen wants to move more investments towards taxation of realised gains. To help pay for that change, the cabinet proposed lowering tax-free thresholds in box 3. Opposition parties objected to the effect on smaller savers and investors, and VVD and CDA lawmakers raised concerns too. Heinen acknowledged the problem on Thursday and promised to seek a different threshold before the Tax Plan is debated. Raising that threshold would require another source of revenue. The political agreement on how to tax gains is proving easier than agreement on who funds the transition.
🟦 What would make opposition support durable?
The parties are asking for different things from the same budget. PRO wants a broader agreement, backed in both chambers, with a substantial shift in taxation from labour towards capital. Volt is positive about the social security change but says it has not signed off on the wider Tax Plan. JA21 wants relief for working households and remains unwilling to promise support on the basis of a single concession. These positions leave room for negotiation. They also make each proposed source of funding a political choice that must be defended across the whole package.
🟦 Are the parties arguing over the same time horizon?
In the financial debate, JA21 warned about rising interest costs and the long-term growth of care and social security spending. PRO argued that fiscal debt is only one measure of what the country leaves behind, pointing also to climate commitments. Both are asking who will bear future costs, while proposing different answers. A budget deal can pass one year’s vote without settling that disagreement. The cabinet needs to explain which obligations it intends to meet now, which it will negotiate later and what happens if the expected savings fail to arrive.
🟦 Where does Europe enter the calculation?
The same tension surfaced in the debate over Europe’s next budget. Heinen argued for tighter EU spending and rejected common borrowing; Volt’s Laurens Dassen warned that holding the budget down could leave too little room for shared investment in security, technology and the green economy. That disagreement belongs in the Dutch budget discussion too. Decisions on defence, energy and industrial capacity extend beyond one parliamentary term and beyond national borders. They need a financing path as credible as the immediate deal.
The Signal
The cabinet has shown that it can respond to opposition demands. Parliament has shown that it will examine the costs of those responses. The next test is whether the government can present the changes as one coherent set of choices: with clear funding, an honest timetable for unresolved reforms and enough support to carry them through both chambers. Until then, every agreement risks becoming the starting point for the next negotiation.
Image credit
Illustration: Altair Media / AI-generated
Caption
As parties move spending and tax measures across the budget, each compromise leaves another question to resolve: where will the money come from?
Category: European Governance, Capital, Featured, Governance, Infrastructure, Insights, Signal · Tags: Box 3, Dutch Budget, European governance, Fiscal Policy, Miljoenennota 2027, Minority Government, Parliamentary Negotiations, Serie - Governing Without a Majority, Social Security
Posted by Altair Media on October 1, 2026 · Leave a Comment
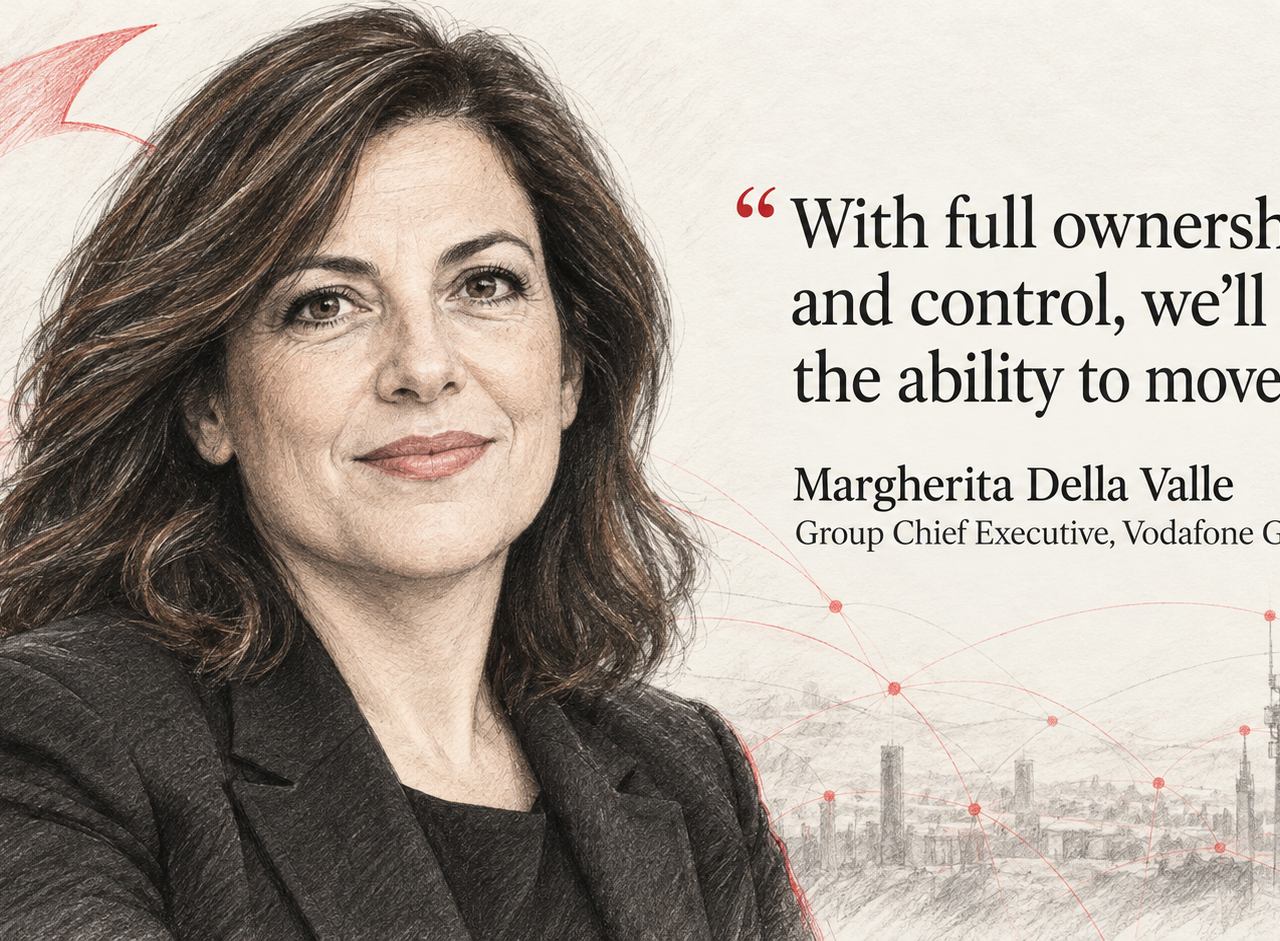
Margherita Della Valle has made Vodafone simpler and taken full control of its UK network. Now she must show that its reach across Europe and Africa can produce lasting returns beyond connectivity.
Vodafone has spent three years reshaping itself. It sold its businesses in Spain and Italy and concentrated on markets where it believes it has the scale to compete. In July, Margherita Della Valle made a different kind of move: Vodafone paid £4.3 billion for its former partner’s stake in VodafoneThree, taking full ownership of Britain’s largest mobile operator.
The decision gives Vodafone more control over an £11 billion UK network investment plan. It also leaves the company carrying the full exposure to whether that investment pays off. In Germany, its largest market by service revenue, the recovery is still delicate. Across Vodafone Business, cloud, security and other digital services are growing. In Africa, financial services show what an operator can build when the network becomes part of a wider daily service.
“With full ownership and control, we’ll have the ability to move faster in the next phase of building one of Europe’s leading networks.”
Margherita Della Valle, CEO, Vodafone Group, on the VodafoneThree buyout.
Together, those businesses make Vodafone a revealing third case alongside Deutsche Telekom and BT. Its challenge is to turn several forms of scale into an economic model that earns more from the capabilities of its networks.
Read More
Category: Featured Headlines, Capital, Digital Infrastructure, Infrastructure, Insights, Perspective, Telecom · Tags: Digital Infrastructure, M-Pesa, Margherita Della Valle, Network APIs, Telecommunications, Vodafone, Vodafone Business, VodafoneThree
Posted by Altair Media on October 1, 2026 · Leave a Comment
European companies are beginning to design systems around photonics. The next industrial test is whether they will commit to buying it at scale.
Grenoble has changed the terms of Europe’s photonics debate. STMicroelectronics is producing silicon photonics on 300 mm wafers, and its expansion plans are backed by long-term capacity reservations. The question is no longer whether Europe can manufacture a photonic chip for the AI economy. It is whether enough European customers will build lasting businesses around that capacity.
For now, the clearest route to scale runs through the global AI market. ST describes its high-volume PIC100 customers as leading hyperscalers; Amazon Web Services has publicly identified itself as a collaborator in developing the technology. Those relationships bring production in France the volumes and commercial discipline it needs. They also give large customers substantial influence over the technology’s direction.
This is Europe’s industrial paradox. Its manufacturers need to sell where demand exists today. European system makers may need more time to develop products they can order at scale. If those schedules diverge for too long, Europe could become an excellent place to make chips for systems specified elsewhere.
If those schedules diverge for too long, Europe could become an excellent place to make chips for systems specified elsewhere.
The European customer is beginning to emerge. The harder question is when that customer will be ready to buy.
Read More
Category: Perspective, Capital, Digital Infrastructure, Featured Headlines, Governance, Infrastructure, Insights, Photonics · Tags: AI infrastructure, European Chips Act, European Industry, Industrial Strategy, Photonics, Semiconductor Manufacturing, silicon photonics, telecom
