Posted by Altair Media on November 7, 2026 · Leave a Comment
Proxima Fusion’s €411 million round advances its stellarator programme. Building a power plant will require a different investment decision.
Proxima Fusion announced a €411 million financing round in July 2026. The German company plans to test a superconducting magnet, build a fusion demonstrator and eventually develop a commercial power plant. Each milestone gives investors something new to assess. The financing question is how far that evidence can take the company, and who will carry the risks that remain.
The first step tests a component. The second brings an entire machine together. The third adds the obligation to deliver electricity reliably and at a price customers will pay. Six questions follow the capital through those decisions.
Read More
Category: Energy Infrastructure, Capital, Energy, European Governance, Featured Headlines, Infrastructure, Insights, Signal, Strategy Governance · Tags: Deep Tech, Fusion Energy, Industrial Finance, Project Finance, Proxima Fusion, Scaleup Europe Fund, Serie - From Breakthrough to Industrial Scale, Stellarators, Superconducting Magnets
Posted by Altair Media on November 4, 2026 · Leave a Comment
What Europe’s payment statistics reveal about fraud, and what they leave out.
Imagine a customer taking a call from someone claiming to work for her bank. The caller tells her that her savings are at risk and urges her to move them to a secure account. She opens the genuine banking app, enters the details and confirms the transfer herself. The bank can verify that she used the app to approve the payment. The caller’s instructions are invisible to it.
Payment service providers in the European Economic Area reported €4.2 billion in fraudulent transactions in 2024, up from €3.5 billion in 2023. Fraud represented about 0.002% of the total value of payments covered by the report. For credit transfers, the distribution of losses tells a different story. Payment service users bore about 85% of the reported fraud losses, according to the joint EBA–ECB report on payment fraud.
A small share of the payment system can represent a large share of someone’s savings. To understand where protection works, we need to follow a case from the initial deception to the receiving account and the eventual loss.
Read More
Category: Signal, Capital, European Governance, Featured Headlines, Financial Governance, Financial Infrastructure, Governance, Infrastructure, Insights, Strategy Governance · Tags: AMLA, Consumer Protection, European Banking, Fraud Reimbursement, Money Mules, Payment Fraud, Serie - AMLA and Europe’s Fraud Defences, Social Engineering, Strong Customer Authentication
Posted by Altair Media on November 3, 2026 · Leave a Comment
Digital banking makes routine decisions easy. The test comes when a customer needs one reconsidered.
Revolut makes everyday banking easy to manage through an app. But a delayed payment or restricted account changes what a customer needs from that interface. A status update may explain that a review is under way. The harder question is whether the customer can submit new evidence, reach someone with authority and obtain a timely decision.
An exception tests the route from the app to someone who can act.
🟦 What happens when the app becomes the door to a disputed decision?
Revolut Group reported 68.3 million retail customers worldwide at the end of 2025. Its Dutch help pages direct customers with questions about account restrictions to support through the app.
At that scale, a clear interface can help customers provide documents and follow a review without repeating their story. The test comes when their case no longer fits the available options.
Can a customer facing a blocked payment find out what information is needed, where to submit it and when someone will consider it? A case marked under review tells the customer where it sits. It gives little indication of what they can do next.
🟦 Can customers tell when a human review would make a difference?
Revolut’s privacy notice says that, depending on the product or service, some decisions may be automated, including through AI without initial human input. It also describes how customers can request a manual review of automated decisions that significantly affect them. That disclosure does not establish how any particular account restriction was decided.
An automated alert, a decision taken with automated assistance and a fully automated decision can look identical on screen. A customer may be asked to provide evidence without knowing which fact is in doubt or which document would help. Even when the bank cannot disclose the details behind a check, it can still make the next step clear.
🟦 Does speaking to a person mean the case can be reopened?
A support agent can explain a status, collect documents or refer a case. Reconsidering a restriction takes access to the evidence, room to challenge an earlier assessment and authority to change the outcome or escalate it to someone who can.
The handover from in-app support to whoever reviews the restriction matters most when new information arrives. Does it reach that reviewer with the original case history intact? Can the reviewer decide that the restriction should be lifted? A conversation can be helpful while the decision itself remains out of reach.
🟦 Can the bank detect risk quickly and correct errors promptly?
In April 2025, the Bank of Lithuania imposed a €3.5 million fine on Revolut Bank UAB following shortcomings in monitoring business relationships and transactions. The finding concerns anti-money-laundering controls. It does not show that AI caused the deficiencies or that particular customers were wrongly restricted.
A bank must detect and investigate suspicious activity. It must also be able to correct an assessment when the evidence changes. Useful measures would include how long restrictions remain after sufficient evidence arrives, how often reviews change the outcome and whether urgent cases are identified promptly.
🟦 Does one app give customers one clear route to redress?
Revolut’s Dutch complaints policy shows why the legal entity matters. Eligible consumer complaints about regulated services provided by its Dutch bank branch can go to Kifid under the applicable conditions. Other services may be provided by different Revolut entities and follow other routes.
The customer encounters one brand. If a case becomes a dispute, the responsible entity and the next step should be as easy to identify as the product was to open. A formal complaint can provide redress. Someone who needs access to their money also needs a route to prompt review.
Signal
Revolut shows how much of banking can fit inside an app. The measure of control is what happens when the standard path fails: whether new evidence reaches a person with authority, whether that person can reopen the case and whether a correction comes in time to matter.
This Signal is part of Who Controls Digital Finance?, an Altair Media Europe series examining who can explain, challenge and correct decisions as banks and financial platforms automate their services.
Credit
Illustration: Altair Media / AI-generated with ChatGPT.
Caption
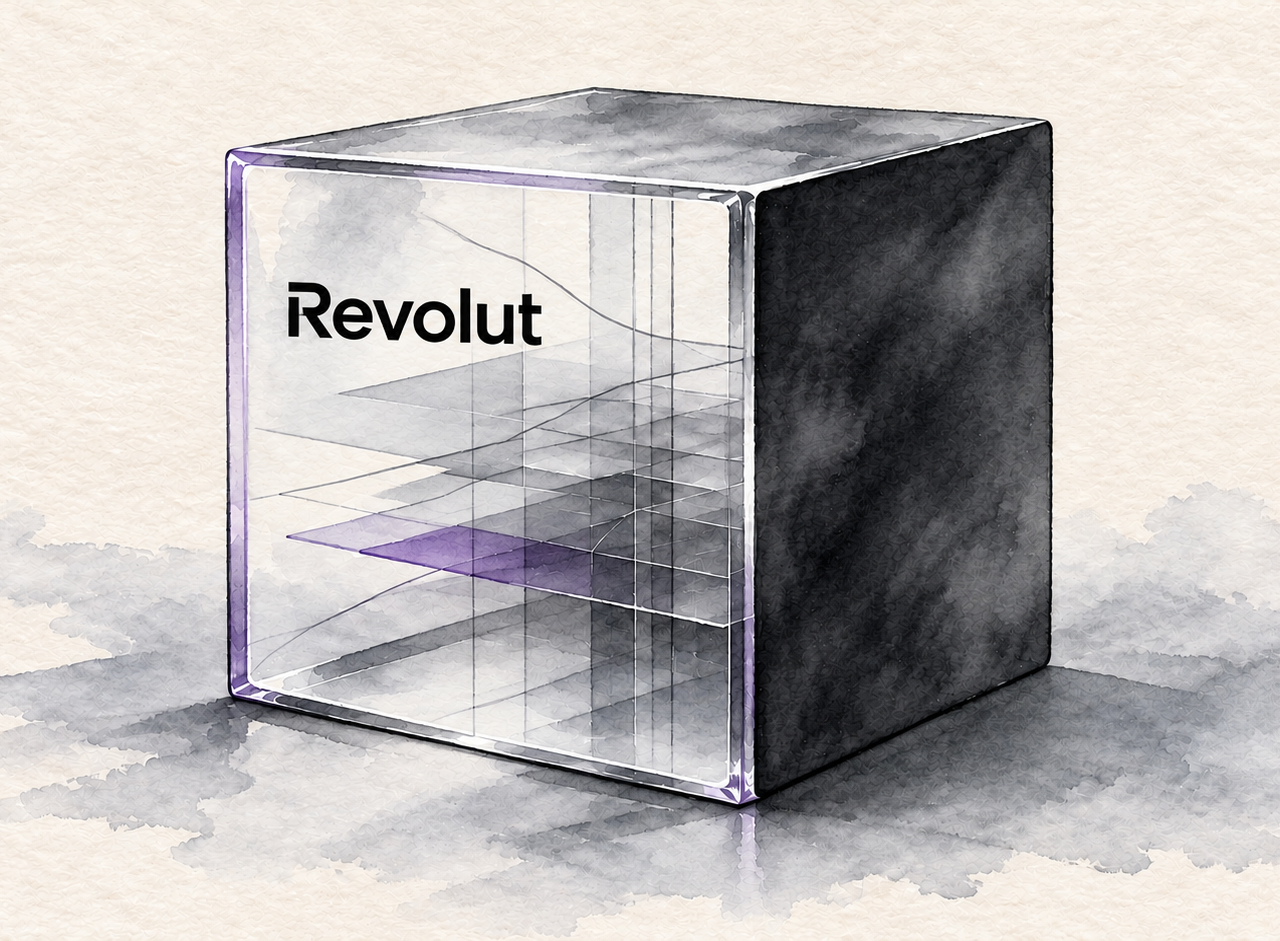
A glass cube bearing the Revolut wordmark pairs transparent layers with an opaque side, illustrating the gap between seeing a case status and reaching someone who can reopen it.
Category: Signal, Capital, European Governance, Featured, Financial Governance, Financial Infrastructure, Governance, Infrastructure, Insights · Tags: Access to Redress, Automated Decision-Making, Consumer Protection, Digital Banking, Financial Regulation, Financial Technology, Human Oversight, Revolut, Serie - Who Controls Digital Finance?
Posted by Altair Media on October 31, 2026 · Leave a Comment
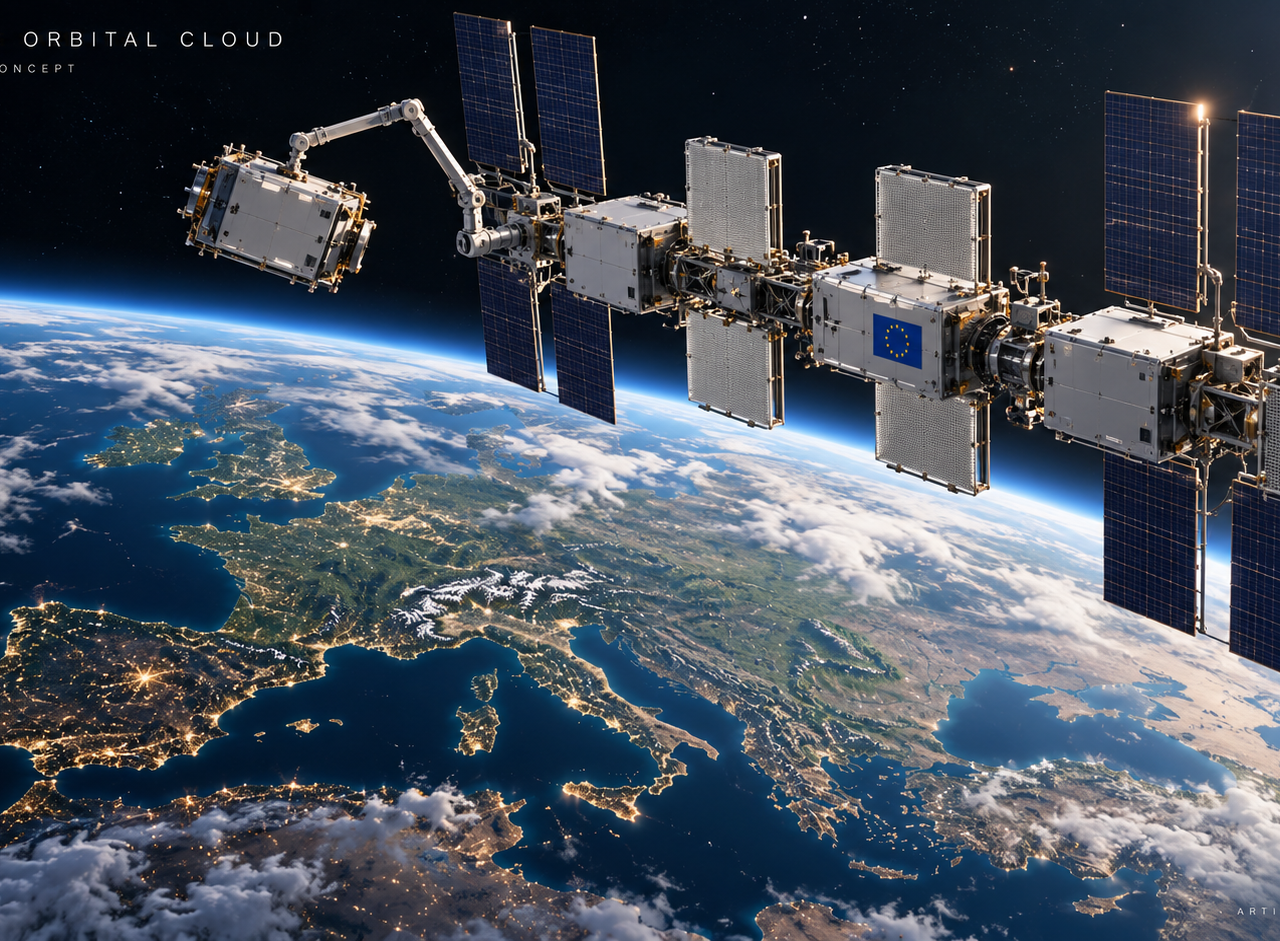
Airbus, Thales Alenia Space and their partners have studied data centres in orbit. Turning that architecture into a service requires customers, capital and an accountable operator.
Airbus, Thales Alenia Space and their partners have studied how Europe could build data centres in orbit. Google’s latest AI demonstration in space gives that work renewed relevance. The European challenge is turning an engineering concept into infrastructure with committed customers, credible financing and an operator responsible for delivering a dependable service.
The Horizon Europe-funded ASCEND study brought spacecraft engineering, computing, cloud services and environmental analysis into one consortium. Six questions determine how that research could support an investable European infrastructure project.
Read More
Category: Signal, Capital, Digital Governance, Digital Infrastructure, Energy, Energy Infrastructure, European Governance, Featured Headlines, Financial Infrastructure, Governance, Infrastructure, Insights, Photonics, Physical Infrastructure, Strategy Governance, Telecom, Transport Infrastructure · Tags: Airbus, ASCEND, cloud infrastructure, Digital Sovereignty, European Space Industry, Orbital Computing, Space economy, Thales Alenia Space
Posted by Altair Media on October 29, 2026 · Leave a Comment
From research grants to growth capital — and the gaps between them
Europe can support a breakthrough with a research grant, help turn it into a product, take an ownership stake in the company and connect it with larger investors. Yet those forms of support do not automatically join up. The European Innovation Council’s (EIC) challenge is to make each funding decision prepare a credible route to the next.
Three questions clarify the journey: who carries the risk, what does the financier receive in return and what must the company already demonstrate? A grant, an investment and a loan provide different answers.
Read More
Category: Signal, Capital, European Governance, Featured Headlines, Financial Governance, Financial Infrastructure, Governance, Infrastructure, Insights, Strategy Governance · Tags: Blended Finance, Deep Tech, European Industry, European Innovation Council, industrial policy, innovation finance, Scale-up Capital, Serie - From European Science to European Industry, Venture Debt
