The Trillion-Euro Flywheel
Europe does not need to find €1 trillion in one place. It needs a financial system capable of making capital move.
SIGNAL | CAPITAL INFRASTRUCTURE – Europe may have quietly solved more of its early-stage deep-tech problem than it realises. A Financial Times chart based on Dealroom data places the European Innovation Council Fund among the world’s most active deep-tech investors. More strikingly, few investors combine its number of investment rounds with such a high concentration in deep technology.
The EIC Fund now has more than 300 companies in its portfolio and has helped establish a sizeable pipeline of European deep-tech businesses. That success creates another problem.
EIC Board member Patrik Sobocki argues that Europe’s remaining scale-up capital gap amounts to at least €1 trillion. The number sounds almost impossibly large if it is imagined as a single pool of money waiting to be found.
That may be the wrong way to look at it. Where will Europe find €1 trillion? Perhaps the better question is: How can Europe build a financial system in which one investment helps mobilise the next?
That is the idea of the flywheel.
🔵 01 | Has Europe’s bottleneck moved?
For years, Europe’s innovation debate began with a familiar complaint: too few start-ups, too little venture capital and too much promising research that never became a scalable company.
That problem has not disappeared. But Europe has become considerably better at identifying promising deep-tech ventures and supporting them through the earliest stages of development.
The EIC is one visible expression of that change. It is funding companies across semiconductors, quantum technologies, biotech, energy, advanced materials and other strategic technologies. The consequence is important.
Europe may increasingly be capable of creating and financing the beginning of the company while remaining much less capable of financing what happens when that company becomes expensive.
A business that once needed €3 million may later need €30 million, then €100 million.and eventually several hundred million to industrialise production, enter global markets or compete with American and Asian rivals.
Europe can successfully create a deep-tech company and still fail to scale it. That is where the bottleneck is moving.
🔵 02 | Why can’t public capital simply fill the gap?
Because that would misunderstand the function of public investment.
The EIC is not supposed to become Europe’s single technology investor. Its more valuable role is catalytic: absorbing part of the early uncertainty, validating promising companies and making subsequent private investment easier.
That means the success of a public euro should not be measured only by where that euro goes. It should also be measured by what it causes to move afterwards.
A public investment can help reduce technological or commercial uncertainty. A private investor then enters. A larger round becomes possible. The company reaches a new stage of development, allowing a different class of investors to participate later.
In that sense, public capital is not meant to replace the market. It is meant to make more of the market possible. And that is where the first rotation of the flywheel begins.
🔵 03 | How does a company climb from €5 million to €500 million?
Europe is now trying to build the missing steps between early venture funding and industrial scale.
The EIC’s STEP Scale Up programme can make investments of between €10 million and €30 million in individual strategic technology companies, helping them raise much larger financing rounds alongside private investors.
Above that sits the new Scaleup Europe Fund, managed by EQT, which is intended to address larger late-stage and growth investments. Taken together, an emerging financing structure begins to appear: early-stage capital → STEP → growth capital → institutional capital
That is the staircase. It describes the journey of one company as its capital requirements increase. But a staircase alone does not create a sustainable financial system. Europe cannot manually push every company up the steps with new public programmes.
The staircase becomes a flywheel only when successful companies return capital, experience and confidence to the financial system — allowing the next generation of companies to climb more easily.
🔵 04 | Where does the €1 trillion actually come from?
Not from Brussels. And probably not from any single European fund.
Europe already has enormous pools of private savings held by pension funds, insurers, asset managers, family offices and other long-term investors. The problem is less the existence of capital than the routes through which it reaches high-risk, long-duration growth companies. That is why Sobocki talks about both GPs and LPs.
General Partners build and operate investment funds. Limited Partners — including pension funds and insurers — provide much of the money those funds deploy.
Europe needs both sides to grow. It needs fund managers capable of making €100 million or €200 million scale-up investments. But those managers can only raise such funds if European institutional investors are willing to allocate substantially more capital to private growth markets. This is where Europe’s fragmented capital market becomes a structural weakness.
Savings remain largely national. Pension systems differ enormously. Stock markets are fragmented. Venture and growth funds are smaller than many US equivalents. Institutional allocations to European growth equity remain limited.
So the €1 trillion should not be imagined as money that must somehow be raised once. It is the cumulative consequence of many more European investors repeatedly financing many more European companies over many years.
🔵 05 | What makes the flywheel turn?
Capital alone will not do it. Deep-tech companies also need customers, manufacturing capacity, specialised talent, energy, procurement, predictable regulation and access to industrial supply chains. But there is another element Europe often underestimates: the exit.
Investment capital eventually has to return. A successful company may reach the public markets. Another may be acquired. A growth investor may sell its stake to a later-stage investor. Whatever the route, investors need credible ways to convert successful investments back into liquid capital.
If Europe’s strongest scale-ups struggle to reach deep public markets, if IPOs remain rare or if the most attractive exit remains a sale to an American buyer, the flywheel weakens.
Pension funds and insurers will not allocate progressively larger sums simply because policymakers ask them to. They need evidence that European technology investment can produce returns.
Those returns finance larger successor funds. Larger funds finance more companies. More successful companies produce more exits. More exits create more confidence among institutional investors.
That circular movement — not one giant capital injection — is the flywheel.
🔵 06 | What would success actually look like?
Probably not a European version of Silicon Valley. And certainly not a €1 trillion cheque. Success would be less dramatic and much more systemic.
An EIC-backed semiconductor company reaches its next financing round without having to move abroad. A €20 million catalytic investment helps unlock a €100 million round. A European growth fund generates competitive returns and raises a larger successor fund. Pension funds gradually increase their allocations because they can see a credible record developing.
A scale-up reaches an IPO or another successful European exit. Part of the capital flows back into the investment ecosystem and finances another generation.
Do that once and the effect is small.
Do it hundreds of times and a market begins to form.
Do it repeatedly for a decade and the numbers become enormous.
That is the difference between the staircase and the flywheel. The staircase helps one company reach the next stage. The flywheel makes the next company easier to finance.
ALTAIR SIGNAL
Europe’s deep-tech bottleneck is shifting from company creation towards industrial scaling.
A €1 trillion gap cannot be filled by public balance sheets, nor does it require a single master fund. EIC, STEP and Scaleup Europe can instead help de-risk companies, mobilise institutional capital and establish the returns needed for repeated reinvestment.
Europe does not need a €1 trillion fund. It needs a trillion-euro flywheel.
Credit
Illustration: Altair Media / OpenAI
Caption
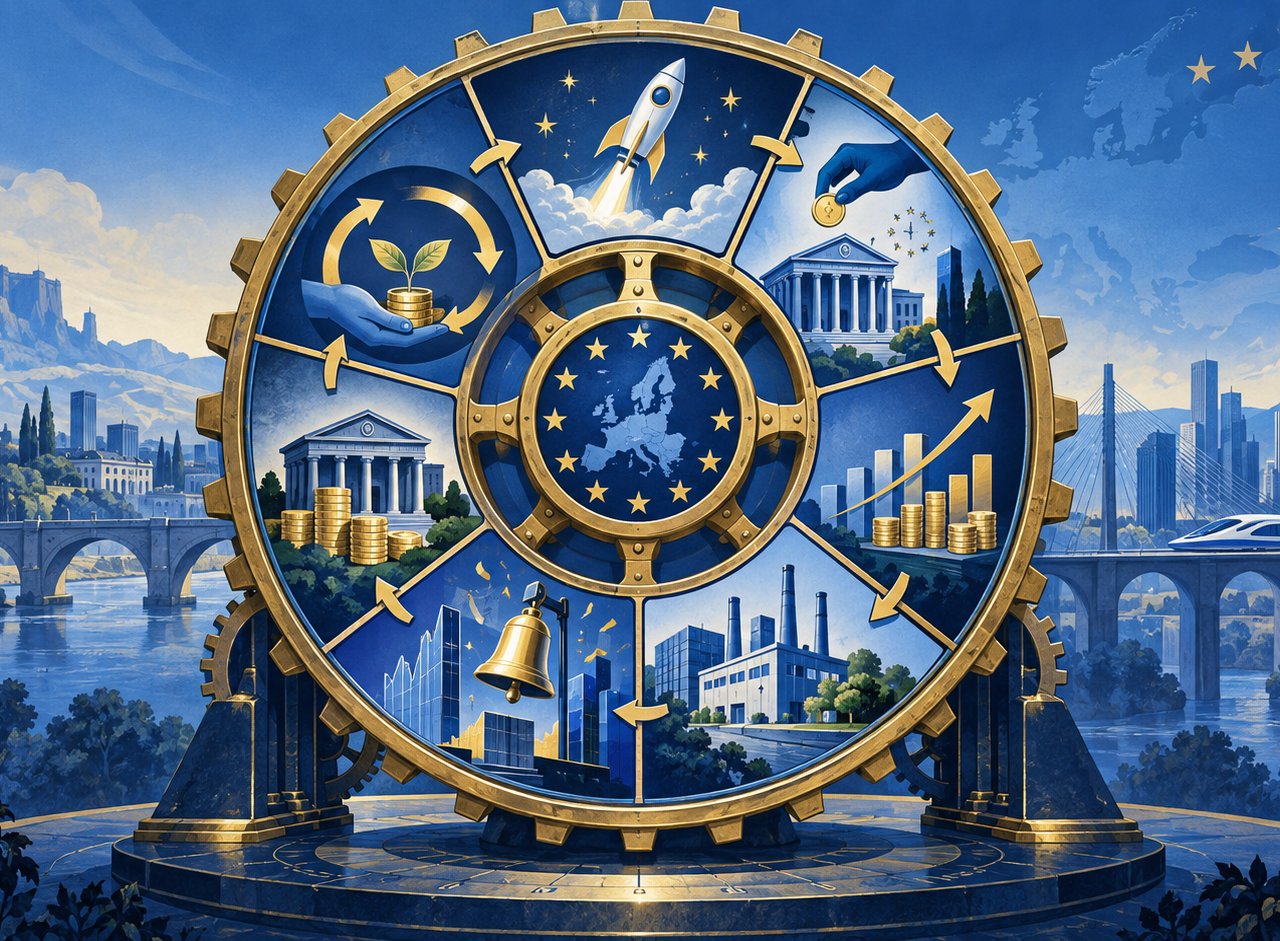
A wheel, not a fund. Europe’s scale-up challenge is not about finding one giant pot of money, but about building a flywheel in which public support, private capital and successful exits reinforce one another over time.