ABN AMRO’s €8.5 Million Question: Who Is Banking Really Serving?
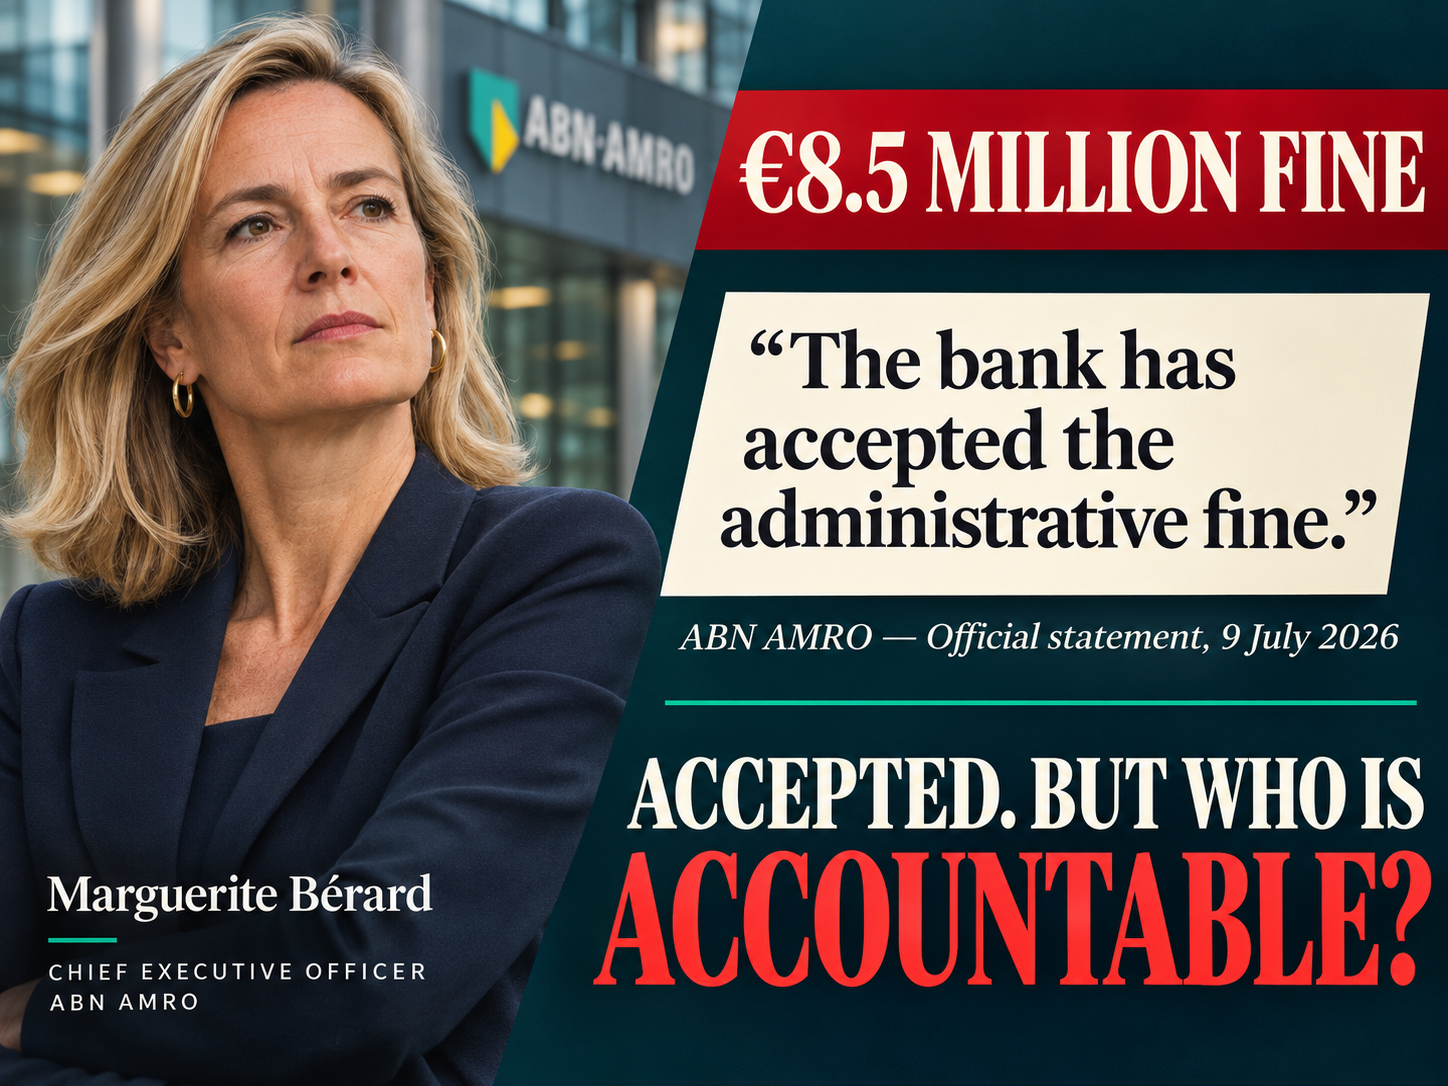
An anti-money-laundering fine raises uncomfortable questions about banking efficiency, customer protection and institutional accountability.
ABN AMRO is accelerating AI adoption while pursuing lower costs and higher returns. Yet in July 2026, Dutch supervisor DNB imposed an €8.5 million fine for serious anti-money-laundering failures. AI was not identified as the cause; the bank’s controls were inadequate. The case raises a larger question: who is accountable when banking becomes more automated, but customers remain exposed?
The enforcement findings, alongside recent ECB research and Dutch studies on fraud and banking accessibility, expose six tensions between commercial performance and the responsibilities of an essential financial institution.
🟦 Why did ABN AMRO allow transactions to continue after identifying unacceptable risk?
On 6 July 2026, De Nederlandsche Bank fined ABN AMRO €8.5 million for serious deficiencies in the monitoring of certain high-risk customers between September 2023 and September 2024.
The supervisor’s investigation identified inadequate customer due diligence, insufficient examination of suspicious transactions and failures to act promptly on available information.
One case was particularly revealing.
A customer’s unusual transaction pattern had been visible for more than two months before ABN AMRO began investigating. Approximately €300,000 had already been received and withdrawn in cash. During the investigation, nearly another €200,000 was received, most of which was also withdrawn.
The bank eventually classified the customer’s risk profile as unacceptable and decided to terminate the relationship.
Yet transactions continued for at least another three weeks. During that period, approximately €60,000 was transferred and €70,000 withdrawn in cash.
DNB also found that some transactions identified as unusual were not reported promptly to the Dutch Financial Intelligence Unit.
The problem was not simply a failure to detect suspicious behaviour. Relevant warning signs had been recognised, but the bank’s investigation and response were inadequate.
ABN AMRO accepted the fine and acknowledged the findings. DNB described the shortcomings as serious and culpable.
The case exposes a fundamental weakness in discussions about increasingly sophisticated banking technology: faster detection has limited value when an institution fails to act decisively.
The tension: Technology can identify financial risks. Only effective institutional action can control them.
🟦 What did ABN AMRO learn from its earlier €480 million settlement?
The latest enforcement action follows a substantial regulatory history.
In April 2021, ABN AMRO accepted a €480 million settlement with the Dutch Public Prosecution Service following serious anti-money-laundering shortcomings covering 2014–2020.
The investigation revealed inadequate customer risk assessments, weaknesses in transaction monitoring and insufficient follow-up of suspicious activity.
One finding concerned approximately 5.5 million retail customers who had been assigned the lowest risk classification through automated analysis of identity information without adequate underlying risk assessment.
This was not a finding about generative AI. It demonstrated an earlier weakness in automated banking controls and their organisational oversight.
ABN AMRO subsequently invested in remediation and strengthened its financial crime prevention organisation. Nevertheless, the 2026 investigation identified serious shortcomings in the ongoing monitoring of certain high-risk customers.
The two cases concern different periods and circumstances. The later fine does not establish that every improvement measure failed. DNB explicitly recognised ABN AMRO’s remediation efforts and constructive cooperation.
However, the recurrence raises questions about institutional learning. Were investigative procedures insufficient? Did escalation mechanisms fail? Was capacity inadequate? And how effectively were completed investigations reviewed?
The published findings establish shortcomings in execution without fully explaining their underlying organisational causes.
Meanwhile, ABN AMRO is accelerating its use of artificial intelligence. According to CEO Marguerite Bérard, more than 85% of employees use AI in their daily work. Its Delphi application supports anti-money-laundering analysts through AI-assisted risk assessments.
Those developments could improve compliance. But adoption figures do not establish better regulatory outcomes.
The relevant evidence would be fewer inadequate investigations, faster escalation and more reliable responses to serious risk indicators.
The tension: Settlements close legal files, but only verifiable operational change demonstrates that an institution has learned.
🟦 If AI makes criminals smarter, why is so much responsibility placed on customers?
The European Central Bank’s November 2026 Financial Stability Review examines how artificial intelligence is transforming cybersecurity.
Its analysis, Decoding the cyber-AI nexus, warns that AI is increasing the capabilities of both attackers and defenders. Financial institutions can improve threat detection, but criminals can automate attacks, develop more convincing deception and exploit increasingly sophisticated digital tools.
Dutch payment fraud statistics underline the challenge, although they do not establish how much fraud directly involved AI.
In 2025, DNB recorded approximately 658,000 fraudulent transactions involving bank transfers, card payments and cash withdrawals, an increase of 30%. Their combined value reached €198 million, up 22%.
Only seven in every 100,000 payments were fraudulent.
That percentage suggests a relatively secure payment system. But the figure says little about the financial consequences for an individual victim. The €198 million represents the gross value of fraudulent transactions, not necessarily the final losses borne by customers.
Banks increasingly rely on transaction monitoring, automated alerts and public awareness campaigns. Customers are encouraged to recognise suspicious calls, distrust unusual requests and terminate conversations when something feels wrong.
Such campaigns are useful. But they cannot substitute for effective protection.
In June 2026, DNB found that criminals can manipulate customers so effectively that warnings are sometimes ignored. The supervisor also identified differences between banks in their willingness to stop suspicious payments.
Banks face a genuine legal dilemma: they generally must execute authorised instructions while exercising a special duty of care when concrete fraud indicators exist.
The parallel with ABN AMRO’s enforcement case is not a legal equivalence, but an operational one. In both financial crime prevention and customer fraud protection, timely intervention can be decisive.
The issue is not whether customers should exercise caution, but how effectively banks respond when caution proves insufficient.
The tension: Banks invest in increasingly sophisticated fraud detection while asking customers to recognise increasingly sophisticated criminals.
🟦 What remains of a bank’s duty of care when its branches disappear?
Digital banking has transformed financial services. Payments are faster, routine activities require less effort and customers can manage their accounts independently.
But the disappearance of physical branches has also changed the relationship between banks and the communities they serve.
For customers who need personal assistance, technological convenience does not automatically mean accessibility.
The Monitor Toegankelijk Bankieren 2026 shows that among the groups studied, the proportion believing their bank offered sufficient assistance increased from 31% in 2023 to 43% in 2025.
The improvement is significant. The remaining gap is equally revealing: fewer than half of the respondents in these groups considered the assistance sufficient.
Research conducted through the Dutch banking accessibility programme also found that more than half of people who cannot manage their banking entirely independently do not know how to contact a bank employee directly.
Population ageing adds urgency. In June 2026, DNB warned that banks must pay greater attention to accessible services as society ages. Older customers are not uniformly digitally vulnerable, but those requiring support face particular challenges when essential financial services are organised primarily through digital channels.
ABN AMRO provides telephone assistance, video appointments and dedicated advisers who can offer help at home. These services are important and demonstrate that human support has not disappeared entirely.
Their existence, however, does not establish how effectively they work in urgent or complex situations.
Can customers facing unexpected account restrictions reach someone with authority to intervene? Can victims of fraud obtain immediate assistance? And can small businesses resolve payment problems without navigating prolonged digital procedures?
A bank’s physical presence once provided a recognisable point of contact. Its digital replacement must offer more than an application and a customer-service number.
The tension: Digital banking improves efficiency for the majority, but essential financial services must remain accessible to those who cannot manage alone.
🟦 Why can banks demand transparency from customers while withholding their own evidence?
Banks have extensive powers to investigate financial activity, request documentation and restrict customer relationships when necessary to meet legal obligations.
Those powers are essential for combating financial crime. They also create an imbalance when customers seek to challenge a bank’s decisions.
A January 2025 ruling by the Dutch Financial Services Complaints Institute, Kifid, illustrates the issue.
The case concerned bunq, not ABN AMRO. The bank had terminated a customer’s payment account following suspicions of unlawful activity. Kifid concluded that the termination was insufficiently justified and ordered the account relationship to be restored.
Yet the committee also ruled that the bank did not have to disclose the detailed results of its internal investigation. Revealing that information could compromise confidential transaction-monitoring methods.
The ruling demonstrates both the effectiveness and limitations of financial consumer protection.
The customer obtained a remedy, but not full access to the information underlying the bank’s decision.
The contrast with ABN AMRO’s enforcement case is significant.
In one case, a bank allowed substantial transactions to continue after identifying an unacceptable risk. In another, a different bank terminated a customer’s account without sufficient justification.
The cases involve different institutions and legal circumstances. Together, however, they expose the difficulty of applying financial crime controls proportionately and consistently.
Banks must prevent illicit activity without unnecessarily excluding legitimate customers from essential services.
As automated analysis becomes more influential, the question of meaningful review becomes more important. Customers need understandable explanations, access to effective complaints procedures and timely correction of unjustified decisions.
Confidentiality rules have legitimate purposes. But protecting monitoring methods should not prevent meaningful independent scrutiny of the decisions those methods support.
The tension: Banks demand extensive transparency from customers, while customers cannot always examine the evidence behind decisions affecting their financial lives.
🟦 Why are banking profits measured more precisely than banking responsibility?
ABN AMRO’s financial ambitions are explicit. Its strategy for 2028 targets return on equity of at least 12%, a cost-to-income ratio below 55% and a net workforce reduction of 5,200 full-time equivalents compared with 2024.
In the third quarter of 2026, the bank reported €940 million in net profit.
These are legitimate commercial objectives. A financially strong bank can invest in resilience, innovation and customer protection.
But profitability is not the only measure of banking performance.
Banks have legally defined responsibilities for financial integrity, reliable payment services and customer protection. Their role as essential financial institutions also creates expectations concerning accessibility, proportionality and accountability.
ABN AMRO publishes information about responsible AI, financial crime prevention and customer assistance. Bérard has emphasised human oversight and the importance of technology delivering value for customers and society.
Yet the bank’s regulatory record makes the effectiveness of those commitments an appropriate subject for scrutiny.
How quickly are serious compliance alerts investigated? How frequently do internal reviews identify inadequate decisions? How long does it take to correct an unjustified account restriction? And how easily can vulnerable customers reach a qualified employee?
These questions call for measurable outcomes, not simply declarations of policy.
The July 2026 violations occurred under the previous CEO, Robert Swaak. Bérard, appointed in April 2025, cannot be held personally responsible for those historical decisions. As current CEO, however, she leads the institution responsible for remediation, governance and the effectiveness of future technological investments.
ABN AMRO accepted DNB’s findings and reported corrective measures. The central question is whether those measures deliver demonstrably stronger controls and better outcomes for customers.
The ECB’s latest research reinforces the importance of governance as AI becomes more deeply embedded in financial operations.
Technology may accelerate banking. It does not transfer responsibility away from the institution.
The tension: Financial efficiency comes with precise targets. Banking responsibility deserves equally credible evidence of effectiveness.
Beyond Efficiency: The Responsibility Test
ABN AMRO’s €8.5 million fine exposes a problem that technological innovation alone cannot resolve. The shortcomings identified by DNB were failures of institutional execution, while the ECB’s latest research demonstrates that AI is making the financial system’s technological risks more complex.
As banks reduce costs, automate processes and withdraw from physical locations, their responsibilities towards customers do not diminish. Financial crime prevention, accessible services and effective legal protection remain essential to public trust.
The real test of intelligent banking is not how efficiently an institution processes transactions, but how effectively it protects customers, fulfils its legal duties and takes responsibility when something goes wrong.
Research and sources
- De Nederlandsche Bank — Official €8.5 million administrative penalty decision, 6 July 2026.
- DNB — Fine for inadequate customer due diligence, 9 July 2026.
- Dutch Public Prosecution Service — ABN AMRO’s €480 million settlement, April 2021.
- ABN AMRO — Official response to DNB’s fine, 9 July 2026.
- ECB — Decoding the cyber-AI nexus, November 2026.
- DNB — More fraud in payments in 2025, June 2026.
- DNB — Banks and payment institutions tackling payment fraud, June 2026.
- Monitor Toegankelijk Bankieren 2026, June 2026.
- Kifid — Bank ordered to restore a payment account, January 2025.
- ABN AMRO — Marguerite Bérard on AI, June 2026.
- ABN AMRO — Roadmap for profitable growth, November 2025.
- ABN AMRO — Third-quarter 2026 results, November 2026.
Image credit
AI-generated editorial illustration © Altair Media, 2026.
Image caption
Accepted. But who is accountable? ABN AMRO CEO Marguerite Bérard alongside the bank’s official acknowledgment of its €8.5 million regulatory fine in July 2026. The illustration highlights the tension between banking efficiency, financial crime prevention and institutional responsibility.
